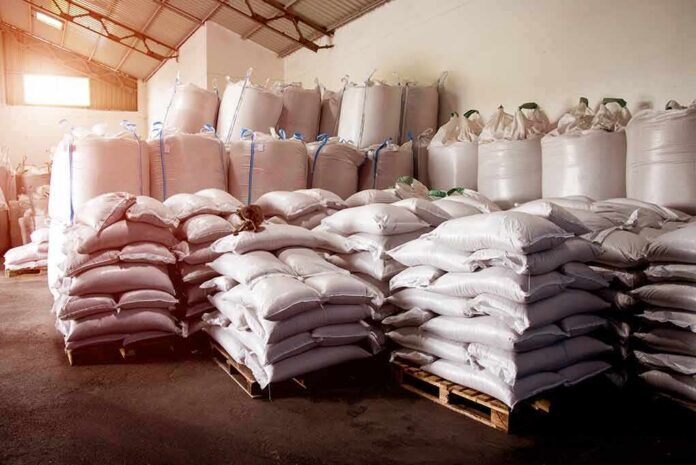
America is rebuilding a strategic cushion for the minerals that underwrite advanced manufacturing and defense, shifting from a just-in-time assumption about global markets to a just-in-case architecture backed by public money, private capital, and onshore storage.
At a Glance
- Washington has launched Project Vault, a new Strategic Critical Minerals Reserve, with Export-Import Bank financing authority up to $10 billion and committed private investment nearing $2 billion.
- The reserve is designed to stock essential raw materials in U.S. facilities and help manufacturers manage supply, processing, storage, and logistics risk.
- In parallel, the longstanding National Defense Stockpile, managed by the Defense Logistics Agency, is procuring select materials such as cobalt after decades of drawdowns.
- Officials have articulated an emergency-readiness rationale, including discussion of target days-of-supply, marking a structural turn back to strategic buffers rather than market-only reliance.
What Washington has actually built: Project Vault and the older defense stockpile
Two distinct efforts now anchor U.S. mineral resilience. First, Project Vault—the Strategic Critical Minerals Reserve—has been formally launched as a supply-chain security initiative financed through the U.S. Export-Import Bank. EXIM approved a loan facility of up to $10 billion, alongside close to $2 billion in private commitments, to establish a reserve that will store essential raw materials in facilities across the United States. The program’s stated remit is broad: de-risking supply, processing, storage, and manufacturer needs, not merely warehousing tonnage for its own sake. Second, the Defense Logistics Agency’s Strategic Materials program continues to operate the National Defense Stockpile, a separate, defense-governed reserve that already holds commodities such as zinc, cobalt, chromium, and select platinum-group metals at U.S. sites.
It is important to separate these initiatives. The National Defense Stockpile (NDS) is a congressionally rooted, DLA-managed instrument for wartime and emergency needs. Project Vault is a newer, public‑private reserve focused on industrial and national-security resilience writ large. They are complementary; they are not the same program. Policy, finance, and governance differ even where commodity targets overlap.
Why now: from drawdowns to restocking
The United States has cycled between accumulation and disposal for nearly a century. Stockpiling authority dates to pre–World War II mobilization; the NDS grew after World War II and the Korean War, then contracted steeply after the Cold War as confidence in global sourcing, allied trade, and substitution took hold. By the late 2010s and early 2020s, the inflation‑adjusted value of the NDS had fallen by more than 90 percent from its around-1990 peak, a reduction reflected in congressional and think‑tank summaries. That long drawdown explains today’s posture: Washington is rebuilding buffers precisely because prior policy assumed markets would deliver under stress—and recent geopolitical episodes, export controls, and pandemic-era disruptions exposed the fragility of that assumption.
Reuters reporting captured the pivot in plain terms: administration officials said mineral stockpiling was under way and discussed emergency-readiness sizing—including a 60-day supply objective in concept—framing the reserve not as speculative commodity hoarding but as a structured continuity tool for manufacturers and defense users. This is a design choice: pick materials that matter, size holdings to plausible shocks, and locate storage in the United States to ensure accessibility when logistics are constrained.
How it will work: materials, procurement, storage, and governance
Project Vault’s mechanism ties public credit to private execution. EXIM’s facility underwrites procurement and storage, while private partners provide capital and commercial expertise across sourcing, processing, and inventory management. The logic is straightforward: leverage market reach to acquire strategic inputs, but bind those inventories to U.S.-based facilities and emergency-access terms. Although the exact commodity slate will evolve, official and public materials repeatedly point to classes like rare earth elements and cobalt—inputs foundational to permanent magnets, high-performance alloys, batteries, and catalysts. The program’s breadth is deliberate: criticality is a function of both material properties and supply concentration; a narrow focus would miss key choke points.
The NDS continues in parallel on a defense footing. DLA Strategic Materials actively stores multiple commodities in U.S. depots and uses targeted solicitations to rebuild or rebalance holdings. A recent cobalt procurement notice—specifying approximately 2,500 short tons of high-purity metal for delivery over multiple years—illustrates how the Pentagon sequences acquisitions for enduring needs rather than spot-market trading. Market conditions can alter timing and lot structure, but the direction of travel is unambiguous: after decades of disposals, the NDS is buying select materials again.
Glencore and Mercuria have each committed $500mm to the founding of Project Vault, a strategic minerals stockpile in the U.S.
The structure is backed by $10bn from the U.S. Export-Import Bank ("EXIM") with Glencore / Mercuria sourcing to build physical inventory of critical…
— Nodal (@nodal_infra) September 26, 2026
Where the genuine complexity lies: defining “enough”
The hard question in strategic stockpiling is not whether to hold inventory but how much, in what form, and where. Days-of-supply targets sound simple; implementation is not. Battery-grade cobalt chemicals versus cobalt metal imply different industrial uses and processing lead times. Rare earths split into light and heavy families with divergent supply chains; oxides, metals, and finished magnets have distinct storage and conversion profiles. Geographic storage inside the United States accelerates access during a shock but adds carrying costs; dispersing across multiple sites reduces single-point failure risk but complicates logistics. Governance matters too: emergency draw rules, rotation policies, and quality assurance determine whether stockpiles function as insurance or become stale artifacts when technology shifts.
Project Vault’s financing and onshore storage mandate answer the “where” and “who pays” questions. The NDS’s targeted solicitations answer the “what” for defense-critical items. The open space is the “how much, in which specification, and how fast can it flow to end users under stress.” That is why the administration’s framing around manufacturer support and emergency supply is consequential: it signals a use-case orientation, not merely inventory optics.
Implications for industry, defense, and policy
For manufacturers, the new reserve architecture offers optionality. A buffer of oxides, metals, and intermediates held domestically can bridge disruptions long enough to pivot suppliers or qualify substitutes. For defense planners, it shortens mobilization timelines by decoupling key munitions and platform components from single-point foreign dependencies. For policymakers, stockpiling is only one leg of the stool; permitting reform, allied co-production, recycling loops, and demand-side efficiency remain essential complements. A reserve covers acute shocks; it does not substitute for diversified, resilient supply chains.
The operational yardstick should be simple and unsentimental: in a plausible disruption—geopolitical, natural disaster, or logistics choke—can U.S. industry and defense meet priority demand for 30–60 days while alternate flows come online? Project Vault and the NDS are being rebuilt to make that answer “yes,” with money and governance attached. The work now is execution—selecting the right materials and specifications, contracting wisely, rotating stock to track technology, and testing drawdown mechanics so that, when the stress arrives, inventories move not just on paper but to the production lines that count.
Sources:
zerohedge.com, dla.mil, whitehouse.gov, exim.gov, defensemedianetwork.com, stripes.com, moulton.house.gov
© featurednews.com 2026. All rights reserved.